A misspelled middle initial on a 1970s deed can stall a Catonsville closing for two weeks. I’ve watched it happen. Most homebuyers pick a title company the way they pick a dentist in a new town, which is whoever got mentioned last. That company checks for liens you may not know about and holds the deposit until closing. It also sends the wire instructions, so you want a company you trust.
What Is Title Insurance in Maryland?
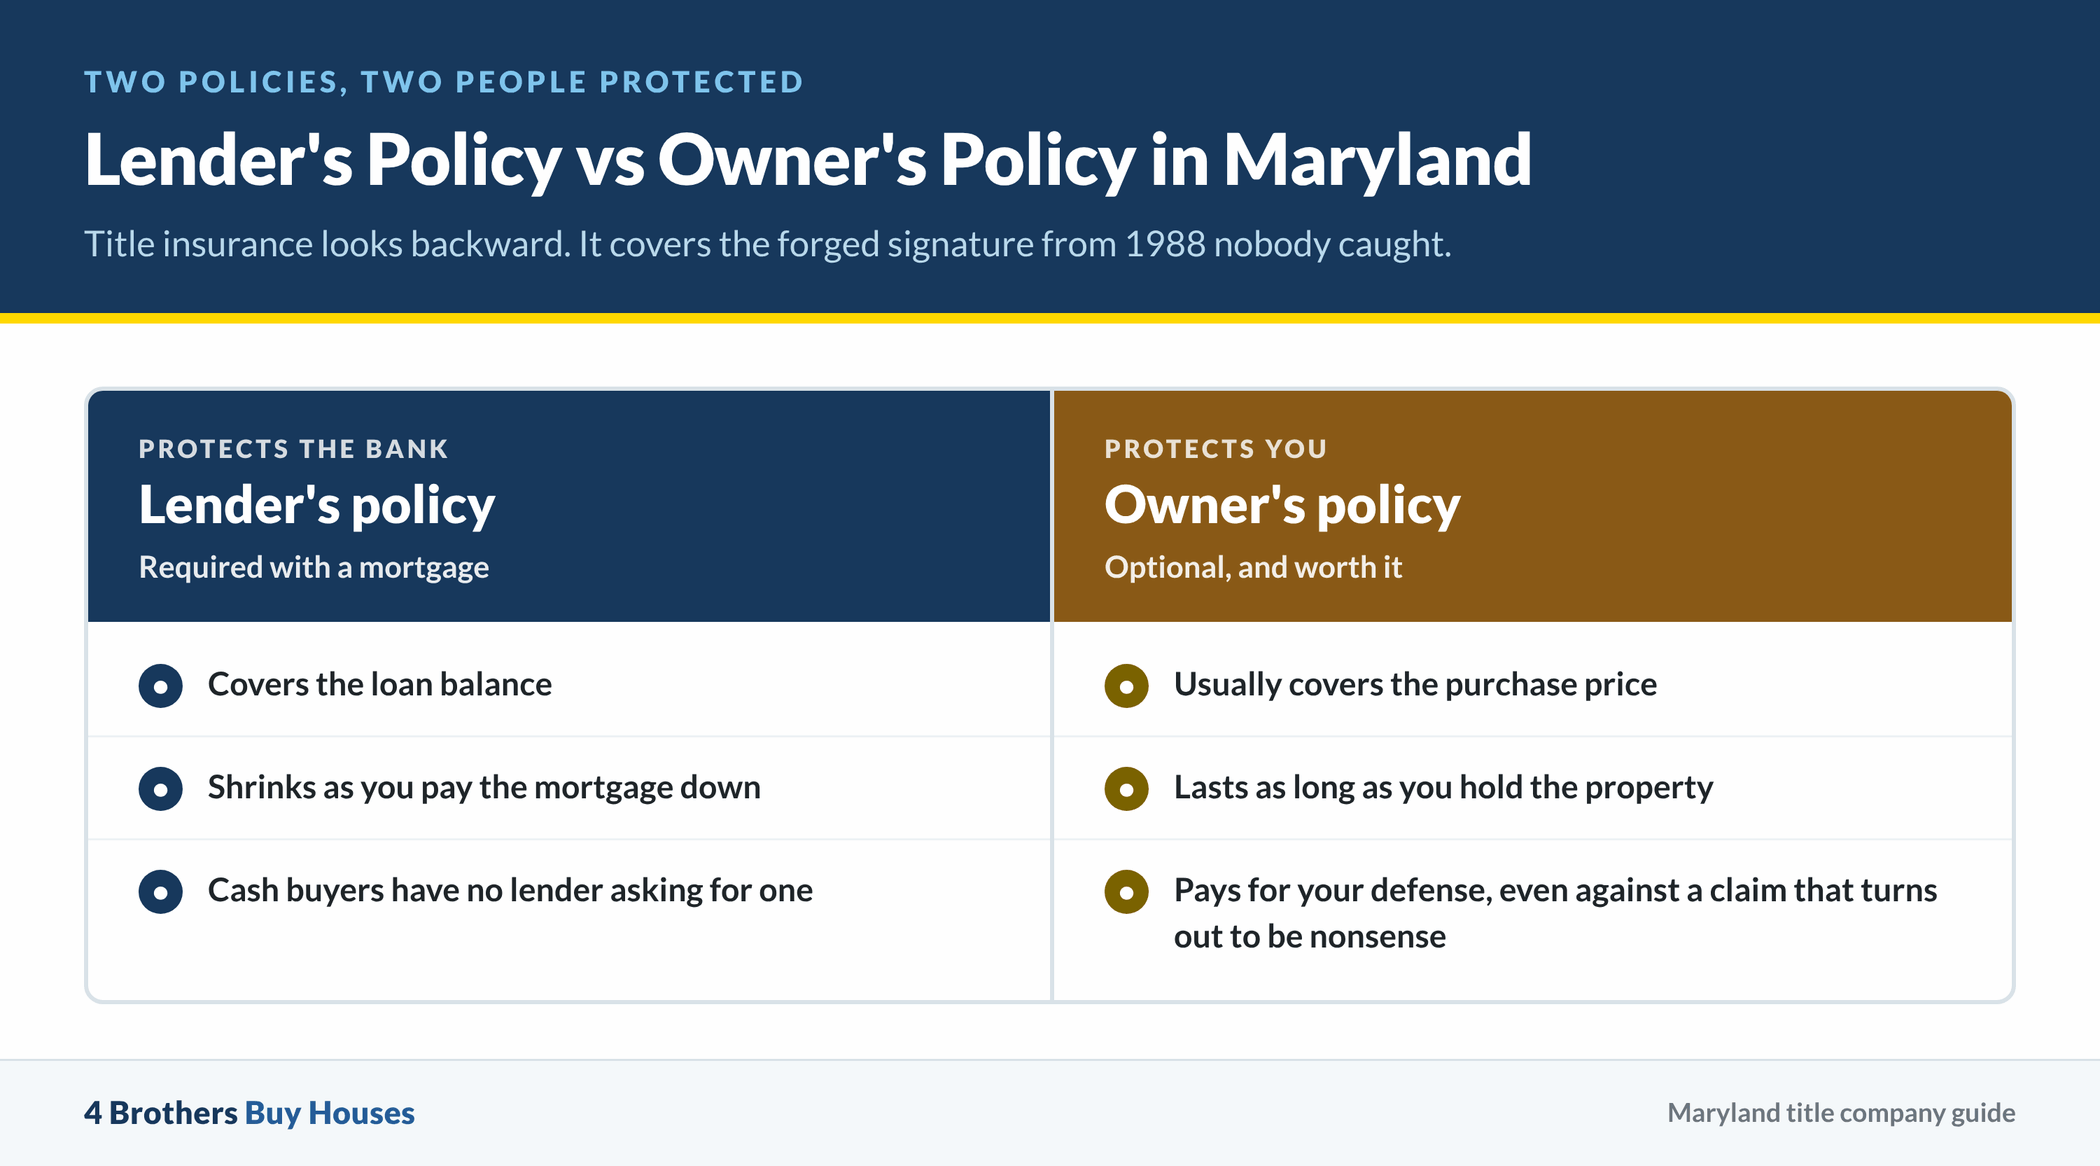
Title insurance looks backward. Homeowner’s insurance covers the kitchen fire that hasn’t happened yet, while this policy covers the forged signature from 1988 that nobody caught. Think missing heirs, an old contractor’s lien or a survey that described the wrong forty feet of land. Your coverage also pays for a lawyer to defend your ownership, even when a claim turns out to be nonsense.
Most Maryland settlements carry two policies, and your title company issues both. The lender’s policy protects the bank and shrinks as you pay down the loan. The owner’s policy protects you for as long as you own the house. Skipping the owner’s policy is the worst savings decision a buyer can make at settlement.
Premiums are a one-time charge, and rates are filed with the state. Everything stacked around the premium varies, from settlement fees to courier charges, so ask for the full cost in writing. Reissue discounts exist too, and they often go unmentioned. If the seller bought a policy within the last several years and can produce it, ask the title company whether your premium drops. Plenty of homebuyers never ask, and the discount quietly disappears.
Who Needs Title Insurance Services in Maryland?
A cash sale has no lender, so there’s no lender’s policy. A title search still matters, since an heir nobody mentioned can turn up and claim a share of the house.
The toughest work shows up on inherited property in Maryland. Estates split among several children and old quitclaims nobody recorded all surface in the land records. Your title company has to clean up each one before a buyer can close. Three siblings in Glen Burnie called me after one got a job transfer with five weeks to move. Their father’s deed still listed a deceased co-owner. Our title company cleared it with an affidavit of heirship before the moving truck left.
Landlords face municipal liens for water or code violations, and those liens follow the property, not the tenant who caused them. Baltimore City rowhouses can also carry ground rent. Tracking down the current ground rent holder can mean reading through fifty years of assignments, and I’ve spent whole afternoons doing exactly that on a single file. Divorcing couples transferring a deed benefit from a title company check before the transfer, not after.
Condos and townhomes in HOA neighborhoods add a community title question. Who owns the common areas, and does the association hold unpaid dues or liens against the unit? A careful title company checks those association records along with the deed.
How Do Real Estate Settlements Work in Maryland?
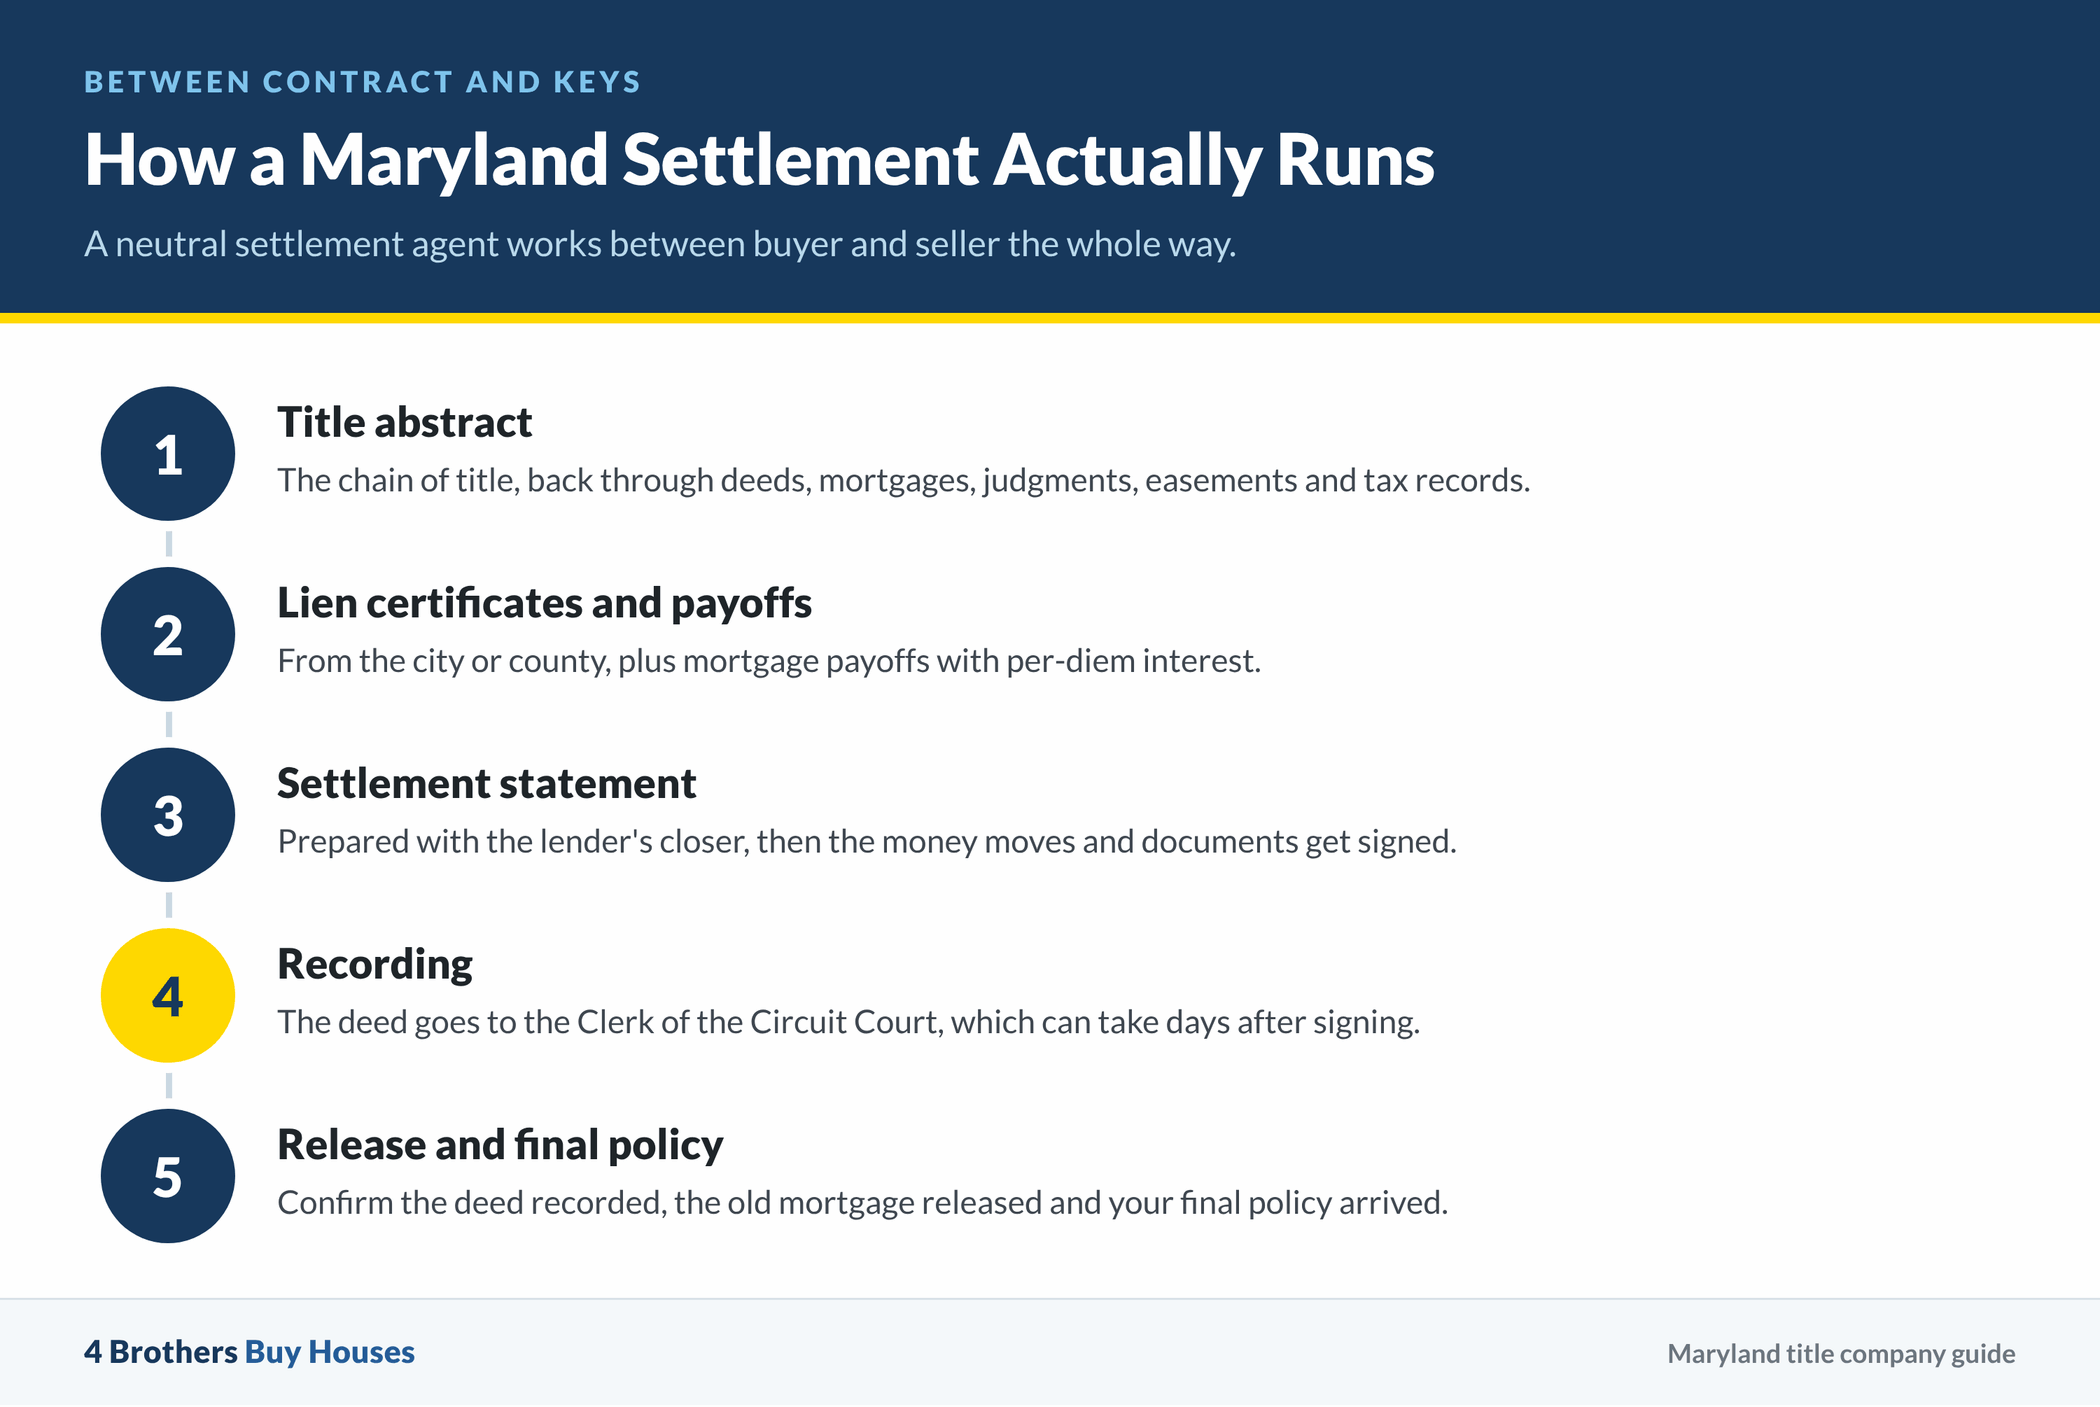
Signing happens at settlement, while recording happens later at the Clerk of the Circuit Court, and that can take days. Your title company tracks the deed until the clerk records it.
A neutral settlement agent runs the closing, and the deed itself has to be prepared by an attorney or a party to the sale. Many of these offices employ counsel or share a lobby with a law firm, which you’ll see in Rockville and Towson.
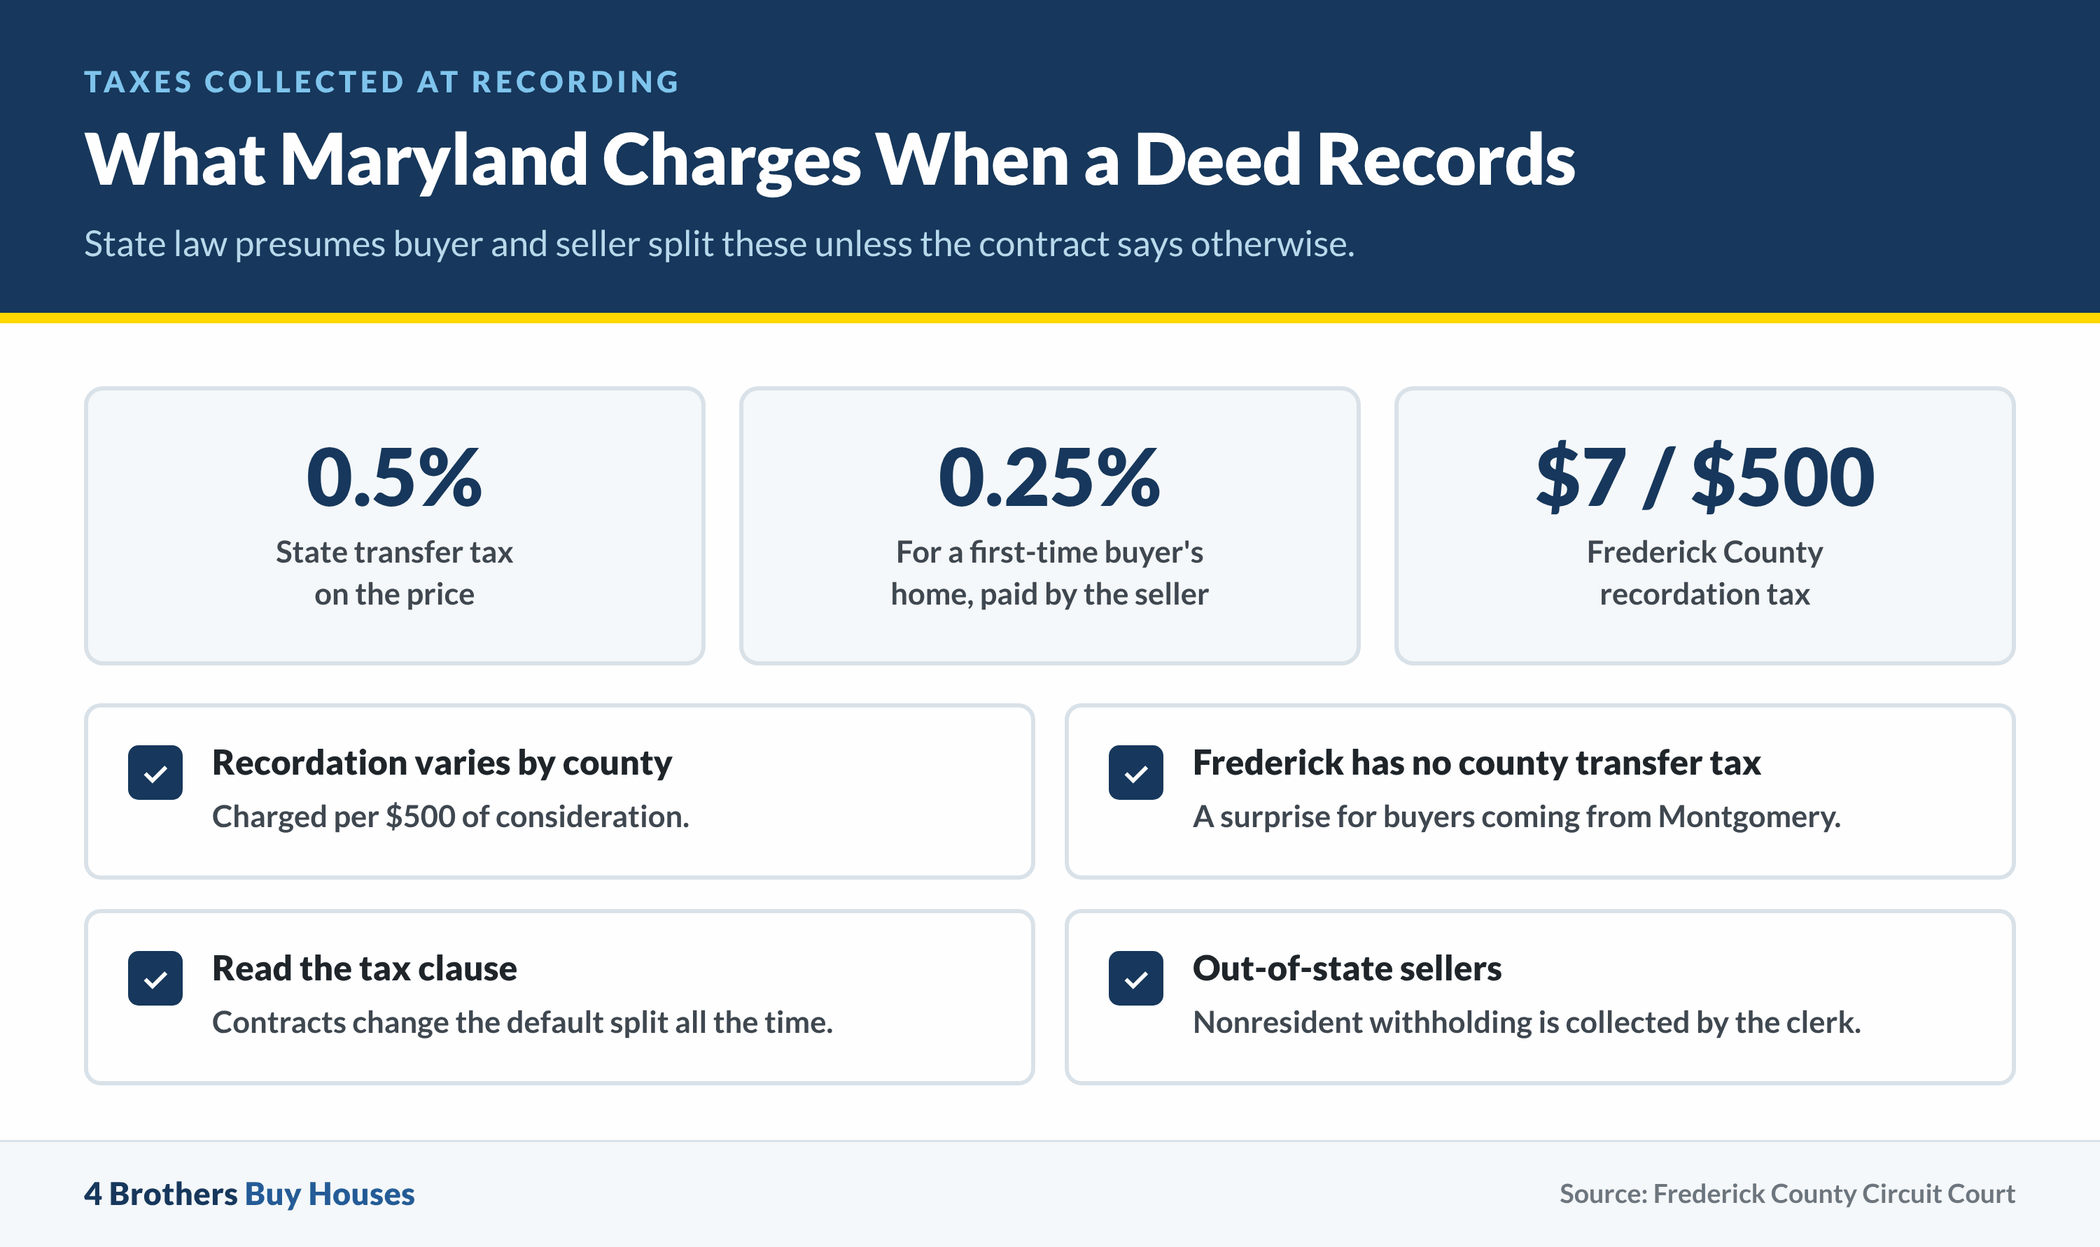
The state transfer tax is half a percent of the price. It drops to a quarter percent for a first-time homebuyer buying a principal residence, and then the seller pays all of it. Recordation tax varies by county. Frederick County’s clerk charges $7 per $500 and has no county transfer tax.
State law splits those taxes evenly unless the contract says otherwise, and contracts often do. Between contract and keys, your title company pulls the abstract and lien certificates, requests mortgage payoffs and prepares the settlement statement. It also holds the escrow deposit until every party signs. In most real estate transactions, that’s the one office touching every document and every dollar.
What Real Estate Services Do Maryland Title Companies Offer?
The title company’s search is the backbone. An abstractor traces deeds, mortgages, judgments and easements through the land records, then flags anything that clouds ownership.
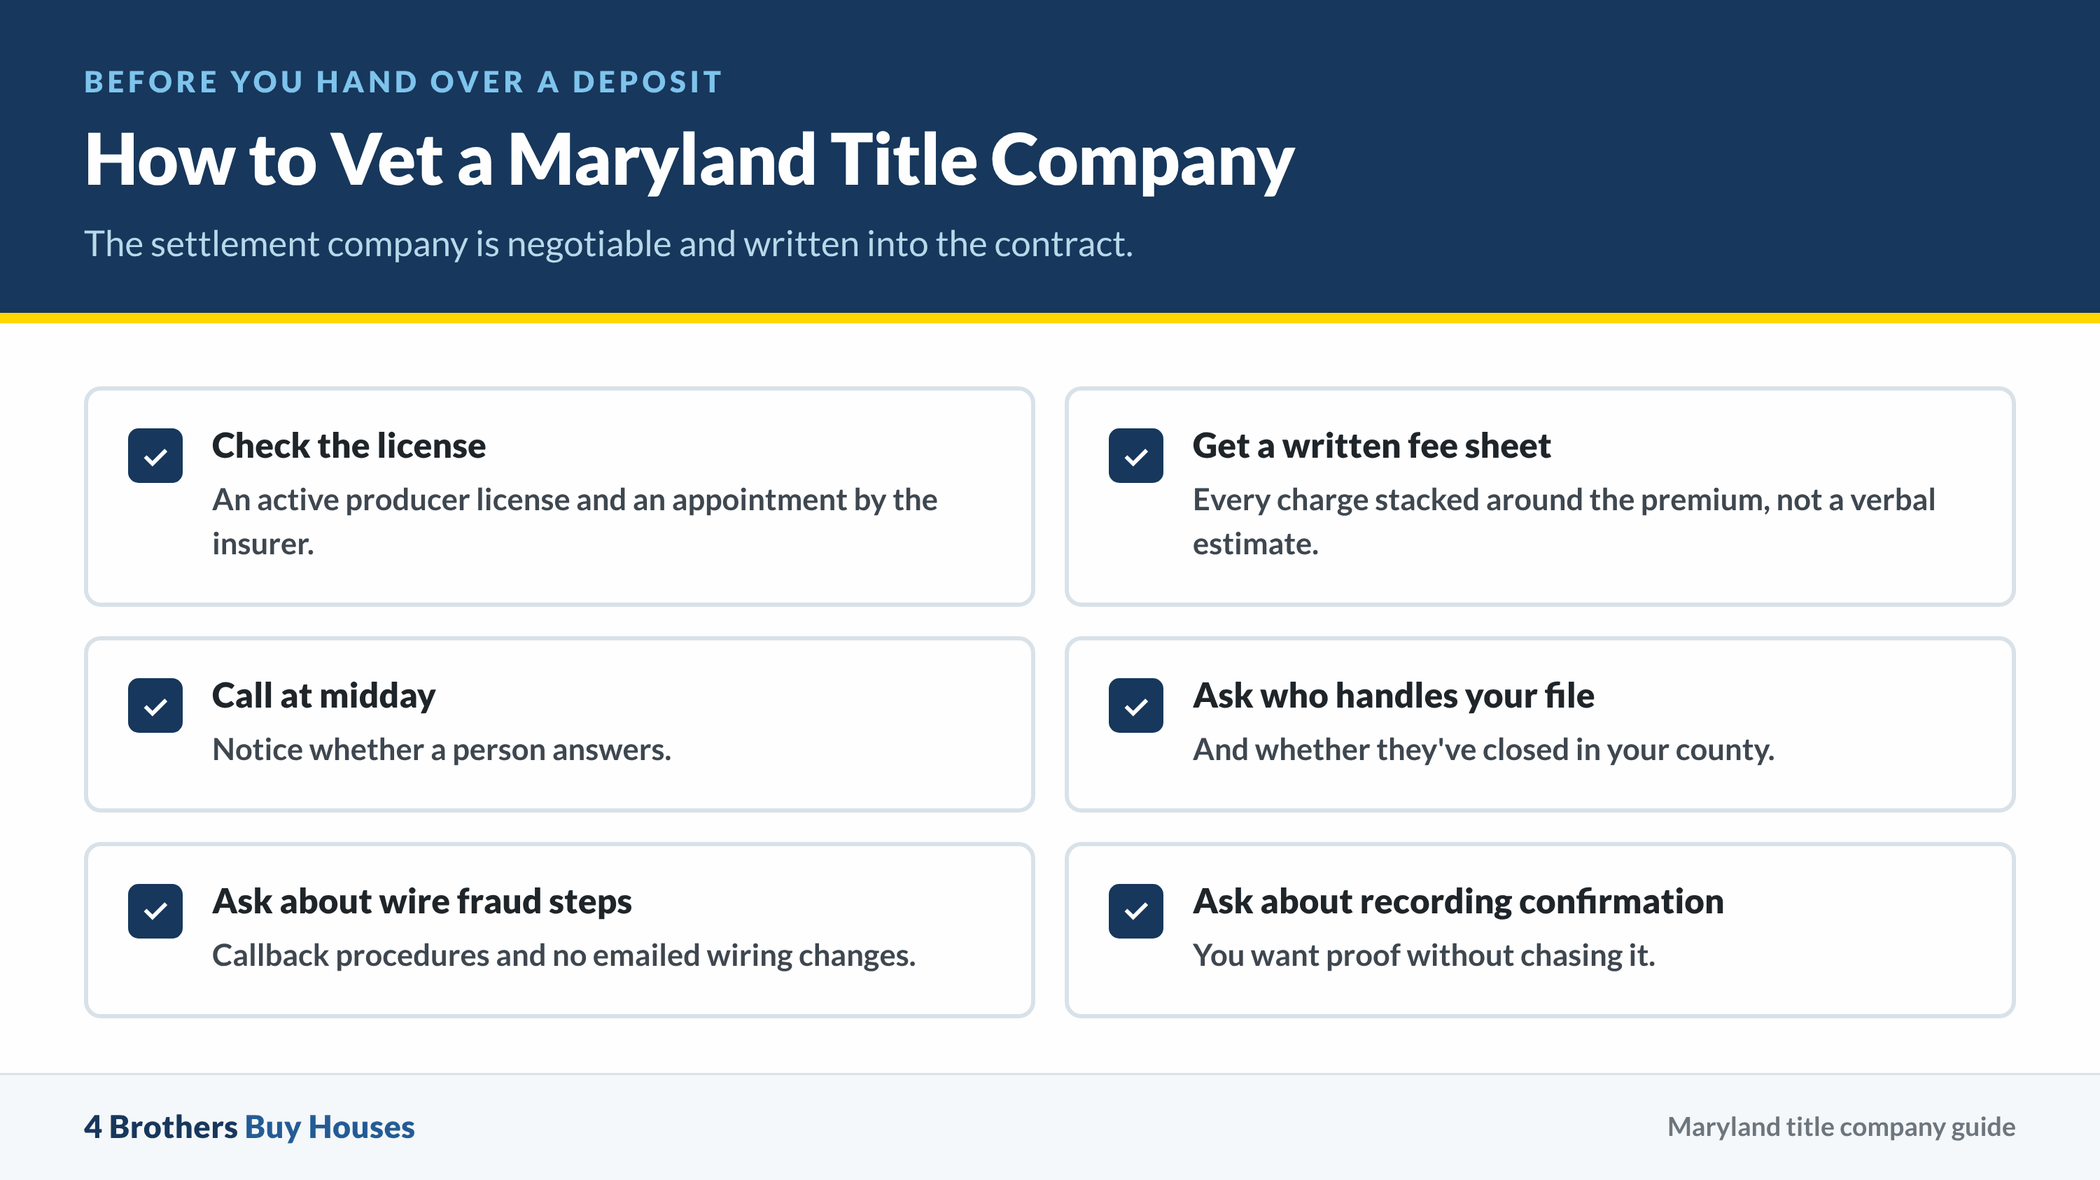
Escrow is the part nobody thinks about until something goes sideways. Your deposit and loan money pass through a trust account governed by state rules, and the title company answers for every dollar in it. Wire fraud protection matters too, and a good title company never emails changed wiring instructions. It tells you to confirm by phone using a number you found yourself.
Settlement day doesn’t finish the title company’s file. Somebody has to confirm the deed recorded and the old mortgage got released. When 4 Brothers Buy Houses buys a house, our title company partners send that recording confirmation without being chased. I’ve seen releases sit unrecorded for months because a file got closed too fast. That loose end lands on whoever owns the house next.
How Do Title Agents in Maryland Partner with Underwriters?
The friendly person running your settlement usually isn’t the company named on your policy. That local title company is a licensed insurance producer. The underwriter is the insurer behind the coverage, and it pays the claims. Your title company searches the records, decides what’s insurable and issues the commitment on the underwriter’s paper. It keeps a cut of the premium for that work.
Producers are licensed by The Maryland Insurance Administration. Applicants need 20 hours of coursework, a passed state exam and a $54 application fee. Each controlling person and anyone handling trust money at a firm needs a personal license. A producer also has to be appointed by the insurer, and you can check both before you hand over a deposit.
A strong underwriter paired with a careless title company still produces files full of surprises.
Which Brands Are Popular for Title Insurance in Maryland?
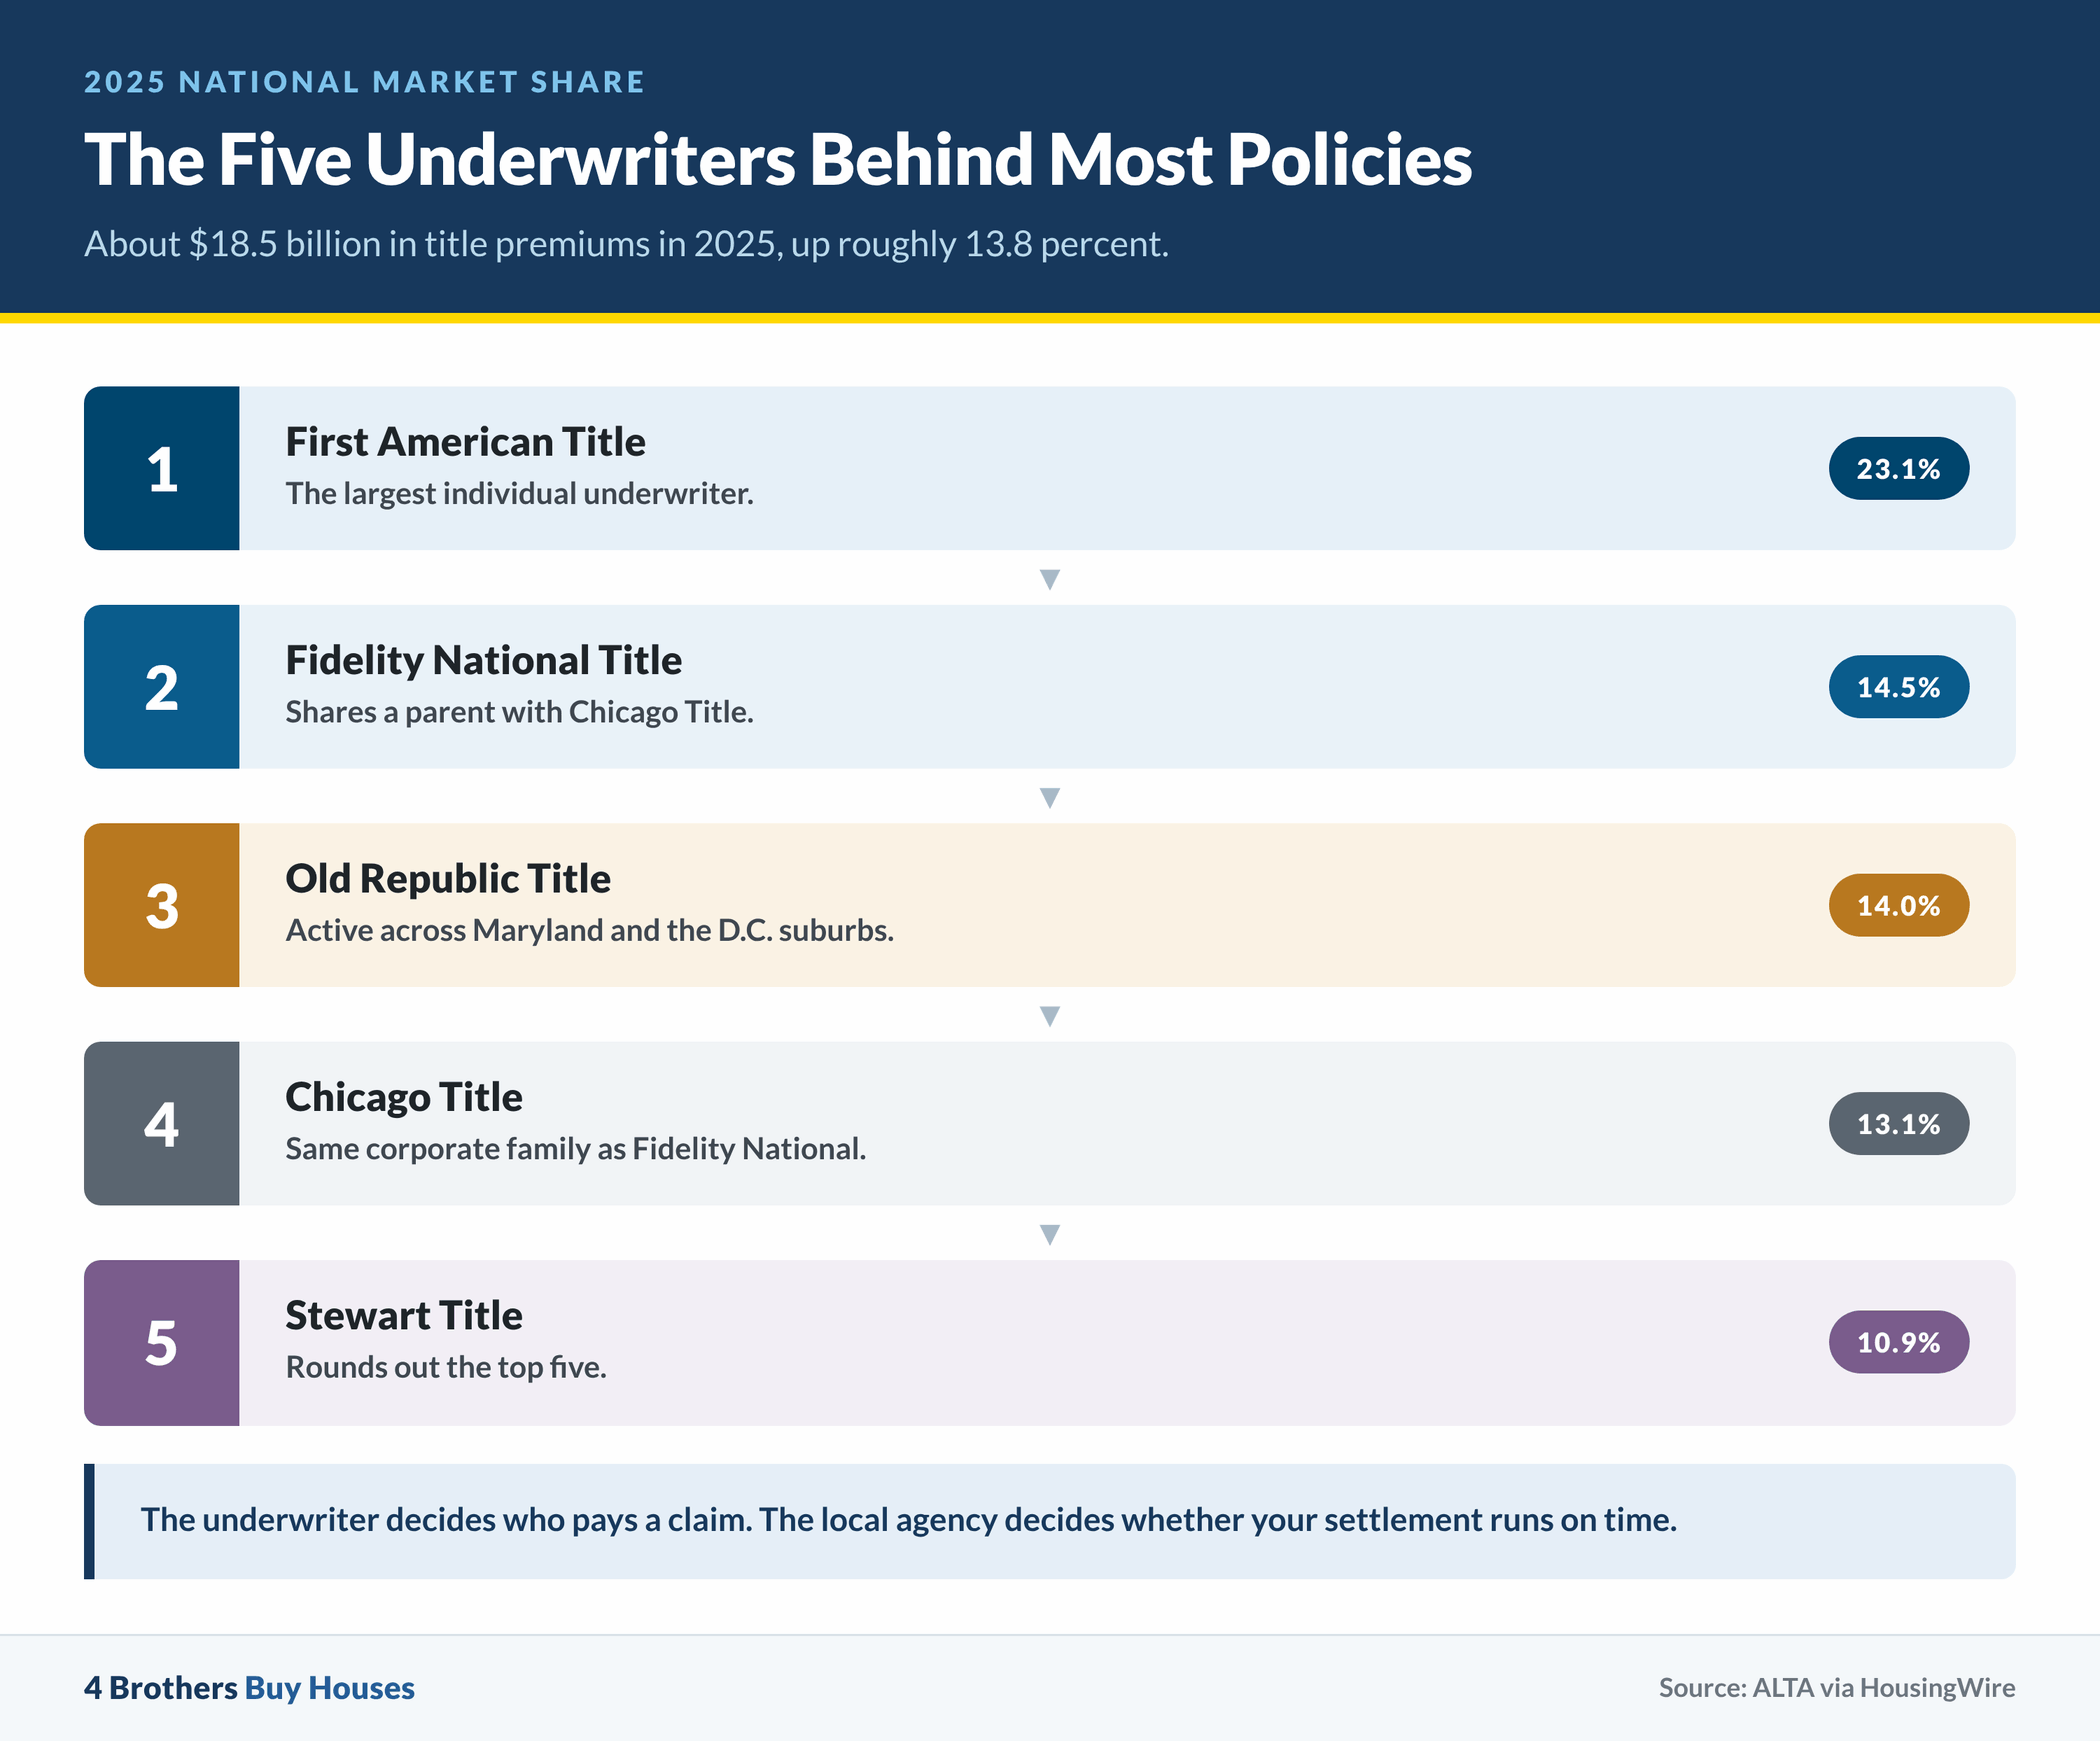
Premiums reached about $18.5 billion nationally in 2025, according to ALTA’s market share analysis. First American led at 23.1 percent, followed by Fidelity National, Old Republic, Chicago Title and Stewart. All of them write policies through title company offices across the state.
My take is that the underwriter matters least. Claims against any major carrier get paid. What changes your experience is the local title company’s turn time and whether someone answers the phone at four on a Friday. Fidelity National and Chicago share a parent company, so the list of truly independent carriers is shorter than it looks.
Ask which underwriter the title company writes for. Then ask how many files your processor carries and how long a clear-to-close usually takes in your county.
Where to Find Title Companies in Maryland
A seller in Hagerstown called me after her lender’s preferred title company pushed her closing three times. Nobody told her she could choose another one. You can, and the choice gets written into the contract. A lender’s recommendation isn’t a requirement, so you’re free to hire your own title company.
Rockville, Annapolis, Columbia, Frederick and Towson all have long-standing independent firms. On the Eastern Shore the pool is smaller, and the abstractors know every family name in the land records. Check the license, get a written fee sheet and ask who’ll handle your file. Then call midday and see whether the title company puts a person on the phone.
Maryland REALTORS reported inventory up 21.3 percent in September 2026, and a slower market gives you time to shop around.
What Do Baltimore Locals Say About Title Companies in Maryland?
A Highlandtown rowhouse sale died in week three over an unreleased 1990s second mortgage. A different title company cleared it and closed thirty-one days later.
City files carry ground rents, water liens and vacant property citations. A title company that works the city every week knows which release forms get rejected. Redfin data shows Baltimore homes averaged 48 days on the market in the three months ending September 2026. A problem your title company finds in week two is a hassle, while one found three days before settlement can cost you the buyer.
The most common Baltimore complaint isn’t fees. It’s a processor who stops returning calls. Saving a hundred dollars on a title company that ghosts you is a bad trade.
A landlord in Essex who’d inherited a duplex he never wanted handed us a shoebox of receipts and asked for a Wednesday settlement, since that was his day off. The title search turned up an old lien from a contractor who’d gone out of business. Our settlement attorney cleared it, and he stopped being a landlord.
Frequently Asked Questions
How Do You Become a Title Agent in Maryland?
Apply to the state insurance regulator, finish the coursework and pass the exam. Then post the bond, pay the fee and get appointed by an insurer before you can sell policies. Firms also need every controlling person licensed.
Who Is the Title Company When You’re Buying a House?
It’s the neutral office that searches ownership history, holds the escrow money, runs settlement and sends the deed for recording. Buyers usually pick the title company unless the contract says otherwise.
Can I Sell a House in Baltimore with a Lien on It?
Yes. Ground rent arrears, water bills and judgments get paid from your proceeds at settlement. A lien found early is a line item, while one found the week of closing becomes a delay.
Do I Need a Real Estate Attorney to Close in Maryland?
Not strictly, since a title company can run settlement here. Probate, divorce or a gap in the ownership chain move faster with an attorney involved. Plenty of Baltimore title company offices keep one on staff, so it’s worth asking.
How Long Does Settlement Take in Baltimore?
Thirty to forty-five days with a mortgage. A cash sale with a clean title can close in about two weeks.
If you own a property that’s become more trouble than it’s worth, it costs nothing to find out what a straightforward sale looks like. Reach out and we’ll give you a straight answer. No pressure either way.
Where We Buy and Close in Maryland
We work with a local title company on every house we buy. We buy houses in Baltimore, Rockville and Frederick. The 4 Brothers Buy Houses team closes across our Maryland service area.
A slower market leaves room to shop settlement services. Redfin counted 5,467 Maryland home sales in August 2026, and the typical house spent 43 days on the market before it went under contract.
Selling a House With Title Headaches?
If you’re selling a property with liens, heirs or a messy chain of title, contact us and we’ll coordinate settlement for you. Here’s how our process works on our side of the table. Use the form below to send the details.
Helpful Maryland Blog Articles
- Selling Partial Ownership Of A House In Maryland
- Tenant Damage vs. Normal Wear And Tear In Maryland Rental Properties
- Who Pays For Appraisal And Inspection In Maryland
- How To Successfully Sell Your House At Auction In Maryland
- Can An Executor Sell Property In Maryland
- Can A Seller Legally Back Out Of A Real Estate Contract In Maryland?
- Selling Your Maryland Home With An Incarcerated Spouse
- Can You Sell a House With Water Damage in Maryland
- How to Sell a House in Foreclosure in Maryland
- Selling a house in probate in Maryland
- How to Sell an Inherited House in Maryland
- Selling A House With Unpermitted Work In Maryland
- When Is the Best Time to Sell a House in Maryland