You’ve heard that buyers won’t pay for somebody else’s taste. That’s mostly right, though it’s only half the story, because nobody pays you back for the quartz you fell in love with. A dated kitchen, on the other hand, can pull more off your offer than fresh cabinet fronts would have cost. Both are true, which is why there’s no clean yes or no here.
So ask a sharper question: will this renovation add more value than it costs me in money, time, and risk? Most sellers check whether a job adds value and stop there. A project can raise your sale price and still be a bad call if it means carrying the house through another season.
The market matters too, and national sales data shows homes nationwide selling at a median of $393,895 in September 2026, up 1.3% from a year earlier. The typical home sat 51 days before going under contract. Two extra months of mortgage payments, insurance, and utilities can eat whatever a renovation gains you.
Here’s where I land: a full gut remodel before a sale is almost always a mistake. A cosmetic remodel done fast and cheap is a different animal.
A few years back, the adult children of an elderly homeowner in Hagerstown, Maryland called me on a Thursday morning. Their mom was three months behind on the mortgage, and an auction date was already set. A contractor had just handed them a bid for new cabinets, which struck me as an odd thing to worry about with an auction that close. We closed ahead of the sale date, and her late husband’s table saw stayed in the garage until the family was ready to handle it. If you’re dealing with something similar closer to Frederick, here’s how we buy houses in Frederick, MD.
Picking cabinets wasn’t their mistake. They were solving a cosmetic problem when they had a calendar problem, and I’ve watched that same mix-up trip up a lot of sellers since. Keep it in mind as you read on.
Which Renovations Give You the Best Roi?
Small beats big, and it isn’t close.
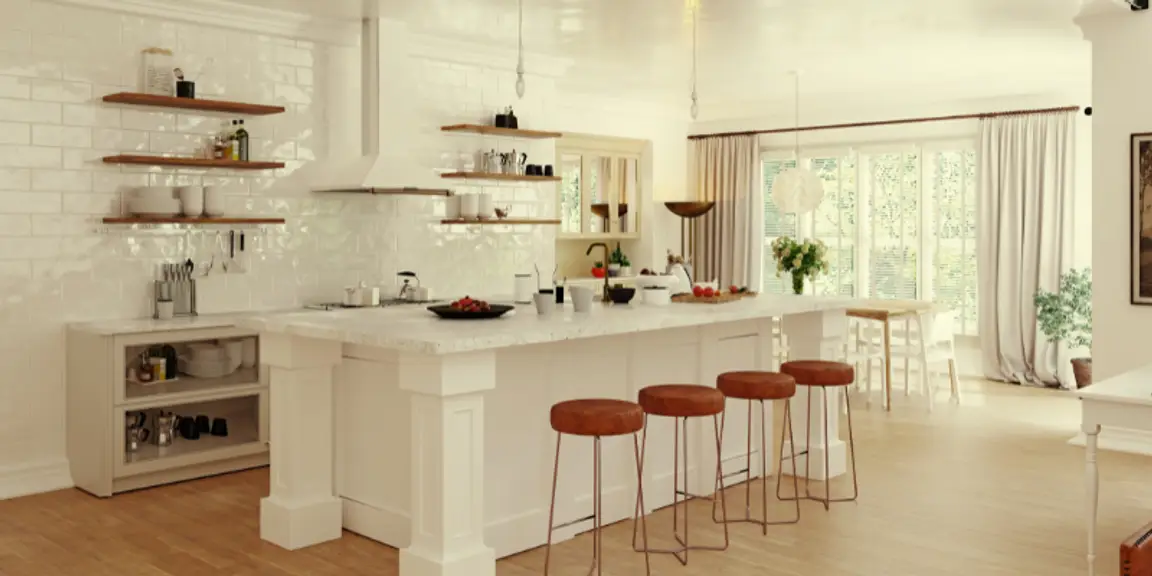
The 2025 Cost vs. Value Report put a minor midrange kitchen remodel at an average job cost of $28,458. It returned about $32,141 at resale, so it’s one of the rare jobs that pays for itself. You keep the boxes, swap the fronts and hardware, add a new range and counters, and refresh the flooring. Nothing moves, and no walls come down.
That’s the whole trick, because once a wall moves, you’re into framing, wiring, drywall, and inspections, and the budget stops behaving. A remodel that stays inside the old footprint has steady costs, since the surprises hide behind the walls.
A major midrange kitchen remodel tells a different story. That job averaged $82,793, and sellers got back roughly half, so you spend nearly triple and recoup a fraction. Buyers don’t value your new layout the way your contractor’s invoice does.
Think about how a buyer sees it. Someone walking into a freshly redone kitchen doesn’t think about the eighty grand you spent. They think “nice kitchen” and head for the bedrooms. Meanwhile, the appraiser is looking at recent sales on your side of town, and a high-end kitchen in a mid-range subdivision doesn’t create a comp that wasn’t there before. You can over-improve for your street, and the market won’t pay you a higher price for it.
Bathrooms land in about the same spot. A midrange bath remodel averaged $26,138 and added around $20,915 in resale value, so you’d get back about four-fifths. Smaller fixes make more sense, so swap a corroded shower head, replace a cloudy shower door, and re-caulk the surround. That’s a weekend of work, and it tells a buyer the house was looked after.
What spooks buyers in a bathroom is any sign that water got where it shouldn’t. Think soft flooring at the base of the toilet, a stained ceiling in the room below, or grout gone black in the corners. Those hint at hidden damage, and buyers price hidden damage on the gloomy side because they can’t see where it ends. Fix the sign, even if you skip the full bathroom remodel.
Outside jobs quietly beat almost everything inside. Garage door replacement topped the same report at roughly 268% recouped. Fresh mulch, trimmed shrubs, and a clean front door cost a couple hundred dollars and change the mood of a showing before anyone reaches the porch. Curb appeal is the cheapest lever you’ve got.
Picture how a showing starts. A buyer pulls up, sits in the car for a minute, and takes in the yard and the siding. They’ve formed a first impression before the agent gets the lockbox open. Everything after that either backs it up or fights it. So power-wash the siding and walkway, straighten the house numbers, swap out a sun-bleached mailbox, and put a working bulb in the porch light. Each one is an afternoon job, and together they shape the story a buyer tells themselves on the way to the front door.
Inside, refinish the hardwood, paint in a neutral tone, and add new cabinet pulls. That’s the list. Anything past it is for you, and the buyer won’t pay for it.
There’s one real exception. If something in the house is broken in a way that could block financing, fixing it is a must. FHA appraisers flag missing handrails, and FHA wants a roof with at least two years of life left. Problems like these can stop a buyer’s loan cold. Repairing them has little to do with return on investment, since it decides whether a financed buyer can close at all.
How Do You Pay for Renovations with No Income?
Contractors want a deposit before work starts, and the money from your sale doesn’t exist yet. That gap is where most renovation plans quietly die, usually before anyone has picked a paint color. A seller on a fixed income, between jobs, or recently widowed can’t float twenty thousand dollars for three months. Hoping the appraisal cooperates while the bills keep coming isn’t much of a plan.
A home equity line of credit is the usual answer, and it works when it works. Lenders will pull your credit, check your debt-to-income ratio, and ask for proof of income, which is the exact thing you’re short on. Some lenders will count retirement payouts and Social Security. Underwriting also takes weeks, and you’ll pay interest on the draw while the house sits.
People also forget that a HELOC is a lien. When you sell, it gets paid off at closing along with your first mortgage. The title company will need a payoff statement, and the account has to be frozen so nobody draws on it. That won’t sink anything, but it’s one more moving part on a day you’d like to keep simple.
Other routes exist. Some agents run renovation concierge programs that front repair costs and collect at closing. Credit cards can cover paint and a shower curtain, though they’re a poor fit for countertops.
If you try a concierge program, read what happens if the house doesn’t sell. Ask whether the money comes due on a fixed timeline even without a closing, and find out who picks and supervises the contractors. Check whether you’re locked into a listing agreement for a set period. I’ve seen these programs help a seller with a solid house and tight cash. They help less when the house needs more than cosmetic work.
Then there’s the family loan. If an adult child is fronting repair money on a parent’s house, write the terms down. Spell out who gets repaid first at closing, from which funds, and what happens if the sale price comes in low. Siblings tend to remember verbal handshakes differently, especially once an estate is involved.
I’d push back on the idea that you have to borrow at all. Selling as-is to a cash buyer like 4 Brothers Buy Houses skips the financing question, because the renovation money comes out of someone else’s pocket. You give up some of the top-line price, and in return you get speed, a firm timeline, and nothing out of pocket. For a seller without cash reserves, that trade often nets out better than a HELOC plus two months of carrying costs.
Net-to-seller is the number most people skip. Take the list price and subtract commissions and any repair credits from the inspection, then subtract the months of carrying costs and whatever you borrowed, plus interest. Write both columns out on paper. Sometimes the listing price still wins by a comfortable margin, and when it does, go list with confidence. Either way, you should know the real gap before you sign a contractor’s deposit check.
Pro Tips for Every Home Seller
Carrying costs are where sellers get sloppy. Every month a house sits, you’re paying the mortgage, taxes, insurance, and utilities on a house you’ve mentally left. Run that number before you sign up for a six-week kitchen remodel.
Add up the real line items, including the ones you forget. That means principal and interest, property taxes, homeowners insurance, power, gas, water, lawn care, and any HOA dues. If the house will be vacant, call your insurer before you move out, since many policies treat an empty home differently.
Order your work by what a buyer sees in the first ninety seconds. Start with the front door, then the entry, the kitchen, and the main bath. A sparkling basement nobody photographs won’t move your price.
Light is the most underrated tool in those first ninety seconds. Open every blind, replace the dim bulbs, and match the color of the bulbs within each room so the photos don’t look patchy. A buyer in a bright, tidy room will forgive a dated countertop. In a dim one, they start hunting for what else is wrong, and I’ve seen that shift happen in showings more times than I can count.
Deep cleaning and decluttering may do more than any renovation you could book. Empty rooms photograph larger, and a house that smells like nothing at all reads as cared for. It costs a few hundred dollars and a weekend, and in my experience it moves more buyers than a new backsplash.
Start with surfaces and closets. Clear the kitchen counters down to one or two items, and take the magnets and papers off the fridge. Thin out the closets until there’s open space behind the hangers, since buyers open closets, and a packed one says the house is short on storage. Smells matter more than anyone admits. Pets, smoke, and a damp basement are the three that buyers remember in the car. Airing the house out and cleaning the carpets beats any air freshener.
Get a pre-listing inspection first if you suspect anything structural. Hearing about the foundation from the buyer’s inspector two weeks before closing is how contracts fall apart. It’s also how you end up negotiating a price cut from a weak spot.
Finding out early gives you choices: you can fix it, disclose it and price for it, or sell to a buyer who doesn’t mind. Finding out late leaves you one option, and the other side sets the number.
Be realistic about your time, because juggling contractors eats hours like a second job. Maybe you’re also handling an estate, a divorce, or a cross-country move. In that case, the renovation that looks good on paper may cost more in delays and stress than it ever returns at closing. If you’re selling in Baltimore and the calendar already feels tight, you can sell your house fast in Baltimore without booking a single contractor.
Frequently Asked Questions
Does a renovated kitchen actually increase my sale price?
It raises buyer interest more than it raises price. A minor kitchen refresh recoups most of its cost, while a full kitchen remodel usually returns about half of its cost or less. If your kitchen is dated but works fine, clean it, paint the cabinets, and price to match.
Should I fix things the inspector will find anyway?
Fix safety items and active leaks, and disclose the rest. Buyers negotiate known problems with a number you control, which is a much better spot to be in. Surprises get negotiated with a number you don’t.
Is selling as-is the same as selling cheap?
No. As-is means you’re skipping repairs, and it doesn’t mean you’re giving the house away. Cash buyers set their price from the home’s condition and nearby sales. The price cut you accept often lines up with what you’d have spent on repairs, carrying costs, and commissions anyway. If you’d like to know who’s behind the offer before you ask for one, you can read more about our company first.
How long do renovations usually take before listing?
Plan for double your contractor’s estimate. Permits, material delays, and change orders are normal. A six-week remodel stretching to twelve weeks is a common outcome.
What if I can’t afford any repairs at all?
Then skip the remodel entirely. Clean, declutter, and get a cash offer first to set your floor. You can still list with an agent afterward if the number doesn’t work for you.
If you’re weighing a remodel against just being done with the house, it costs nothing to see an as-is offer. Get the number and stack it against your repair estimates and a few months of carrying costs. Then decide from there, on your own schedule. There’s no pressure either way, just better information before you hand anyone a deposit. If you’d like to talk it over first, you can connect with us whenever it suits you.