Every spring, usually on a warm afternoon right after a rain, subterranean termites swarm across this state. Wings pile up on windowsills in Catonsville, in Glen Burnie, in half the bungalows off Route 40. Most folks grab the vacuum and figure it’s handled. That’s where it goes sideways. A vacuum fixes nothing on paper, and paper is what moves a Maryland closing.
So does the state force you to carry a termite bond before you sell? It doesn’t. No Maryland statute puts that on a seller. Stop at the one-word answer, though, and you’ll be flat-footed at the three or four moments where wood-destroying insects decide whether you get paid.
Do You Need a Termite Letter to Sell a House in Maryland
A bond and a letter are two different documents, and sellers lose money confusing them. Someone hears “termite” at the settlement table and assumes one piece of paper covers both jobs. It doesn’t. The mix-up costs time first, then money, right when a closing date is already set. You end up booking an inspection with three days left, paying a rush fee, hoping nothing turns up.
Think of a bond as a service contract with a pest control company. They treat the house, come back yearly, and re-treat if the colony returns. Some cover repairs to damage found later. Plenty don’t, so read the fine print before you lean on it. A letter is a one-day snapshot of what a licensed inspector could see, signed and dated. That date carries weight, because a letter from two years ago does you no good. One protects you going forward. The other records what was true that morning.
Buyers ask for the letter. Lenders ask for the letter, and certain loan programs won’t move without it. Almost nobody in a Maryland contract demands the termite bond itself. If you carry a bond, say so, since a buyer may read it as a sign the house has been watched. The inspection still happens either way.
If you’d rather skip the termite inspection process, 4 Brothers Buy Houses can make you a cash offer for the house as-is, with no pressure or obligation.
The Form Your Buyer’s Lender Wants
That letter usually arrives on the NPMA-33, the wood-destroying insect report published by the National Pest Management Association. HUD hosts a copy, and it’s approved for FHA and VA financing. Your inspector records what he finds in accessible areas: live insects, old damage, or conditions that invite a colony back. Scope trips people up. The form defines wood-destroying insects as termites, carpenter ants, carpenter bees, and reinfesting wood-boring beetles. Mold and mildew aren’t on it.
His visit is tamer than most sellers expect. He walks the perimeter, gets into the crawl space, checks the garage, probes sill plates with a screwdriver, and looks where moisture collects. He can only report what he can reach. Boxes stacked against a basement wall or a hatch screwed shut come back as inaccessible areas, and that reads to a nervous buyer like you’re hiding something. Clear a path first.
The line that causes the most grief is conditions conducive to infestation. Mulch heaped against siding. A downspout dumping at the foundation. Firewood on bare ground, crawl space vents choked by shrubs. None of that is termites. All of it invites them, and most of it is a Saturday with a shovel. Handle those items early, and the report stays short. Short is what you want a buyer’s agent reading. Standing water under the house is the expensive version of the same problem, and selling a house with water in the crawl space in Annapolis raises the same buyer questions.
That report isn’t a pass or fail grade. It’s testimony about one day, and it has a shelf life printed on it. The NPMA-33 says outright that it’s invalid for securing a mortgage or settling a transfer if it isn’t used within 90 days of the inspection, and that those 90 days aren’t a warranty. A February inspection won’t carry a June settlement.
VA buyers are the strictest group you’ll handle, and here that isn’t a judgment call. The VA requires a wood-destroying insect inspection here as a matter of course, because the state sits in the moderate-to-heavy infestation band on its map. Since June 2022, the buyer is allowed to pay for it, which used to be off-limits. FHA works differently. There, the appraiser has to see something first, mud tubes on a foundation wall or chewed wood near the sill, and then a full inspection is required. Most regular lenders follow the same appraiser trigger. Maryland cash buyers can offer another route when a seller wants to avoid lender-driven inspection requirements.
What Maryland Law Puts on You Instead
Disclosure is the real legal duty here. Maryland gives sellers a choice: disclose the property’s condition, or disclaim it. Both live on the same state document. We’ve watched plenty of sellers pick disclaimer just to skip the hassle. You can read the Residential Property Disclosure and Disclaimer Statement yourself before your agent slides it across the kitchen table.
Pick the disclaimer, and you’re selling as-is without promising anything about the condition. That’s a fair choice, and we’d argue it’s the right one for a lot of inherited or long-vacant properties. What the disclaimer won’t do is erase a known latent defect. Maryland Real Property § 10-702 sets a two-part test. The problem has to be one a buyer wouldn’t reasonably catch on a careful visual inspection. It also has to pose a direct threat to health or safety. Hidden termite damage can meet both parts. Whether yours does is a question for a Maryland attorney, not a blog post.
The practical version: answer from what you actually know, and don’t speculate about what you don’t. If a company treated the house years ago, say so and staple the invoice to the packet. “Unknown” is a real answer on those forms, and writing it costs you nothing. Sellers get burned by sure answers that turn out wrong far more often than by admitting a limit.
Honest summary: nobody in Annapolis requires you to buy a bond, and everybody expects you to tell the truth about what you know. Keep your receipts, write down what you remember, and let the buyer’s inspector handle the rest. If the paperwork is the part you’d rather hand off, we buy houses in Annapolis, MD and take them with the termite history attached.
If you’d rather avoid the repairs and uncertainty, contact us for a cash offer on your Maryland house. There’s no pressure or obligation, and you can decide what works best for you.
What a Bond Buys You, and What It Doesn’t
Termite bonds come in two tiers. The cheaper one covers re-treatment only. If bugs come back, the company sprays again at no charge. The stronger version adds repair coverage up to a cap, and that’s the tier worth having if you’re staying put.
Renewal pricing in 2026 runs $150 to $500 a year depending on the tier, with re-treatment-only contracts at the bottom of that range and repair coverage at the top. Starting fresh costs more up front, generally $500 to $2,500 for the initial treatment plus the first year. Those figures come from current national cost tracking and from the bond contracts we’ve reviewed on houses we’ve bought.
Here’s where a termite bond earns its keep on a sale: it transfers. A bond that follows the house to the next owner is a selling point you can put in the listing. Most companies will move the bond, usually for a fee, and buyers read it as coverage they didn’t pay for. Ask what that fee is before you assume it’s small.
Before you sign or renew, get answers in writing. Is this re-treatment only, or does it include repairs? Is it transferable, and does the new owner keep your coverage or start a fresh contract? Does the cap apply per claim, or over the life of the bond? What voids it: a grading change, a new deck, an addition, a plumbing leak nobody reported? Does the company require a yearly inspection to keep the warranty alive, or will they mail an invoice and let you assume you’re covered? Selling mid-bond? Call the company yourself once you’re under contract. Don’t leave that errand to a title clerk in the last week before closing.
A lapsed bond is worse than none. Skip a yearly visit, miss a renewal, and the warranty dies quietly while the buyer’s agent finds the old contract in a drawer and starts asking.
Read the coverage cap before you brag about it. We’ve seen bonds where the repair language covers new damage only, excluding everything the inspector wrote down the first time he walked the crawl space.
Treating Before You List, or Not
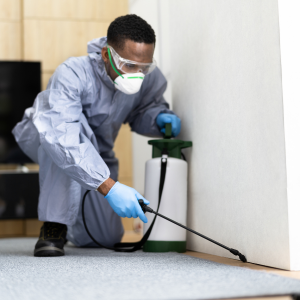
Common advice says treat everything and hand the buyer a clean report. As a universal rule, we disagree. Treatment on a house you’re about to leave is money spent on somebody else’s asset, and the repair work behind it is usually the bigger number anyway. Cash home buyers in Baltimore and surrounding Maryland cities may look at the underlying damage differently.
Sequence matters. Soil-applied liquid termiticide around a foundation stops the colony. It doesn’t restore a chewed-out band joist. Buyers reading a report full of old damage want a structural opinion, not a pest receipt, and now you’re hiring a contractor mid-contract with a settlement date staring at you.
If you do treat, do it before the photos go up. Once a settlement date exists, every delay becomes yours to explain to somebody else’s lender: the applicator’s backlog, a rain day, a carpenter who wants the wall opened before he’ll price it.
Treating makes obvious sense when the colony is active, the damage is cosmetic, and your house sits in a fast submarket like Columbia or Rockville. Skip it when the house needs a gut rehab anyway, when an investor is pricing the work themselves, or when the money isn’t there.
One pattern we keep seeing: sellers spend on treatment, then price the house as though the underlying damage vanished. The next buyer finds the same weakened wood. The report reads the same way. Now there’s less cash in the account than when they started.
How This Plays Out in Negotiations
On termite questions, sellers care more about certainty than price. A buyer who finds evidence during the inspection window usually isn’t trying to walk. They want to know what the fix costs and who pays. Either you have the paperwork, or you don’t. Say the buyer asks for a $3,000 credit toward treatment and repairs. A paid treatment receipt and an active bond give you a real argument for handing over nothing, and we’ve watched sellers pay zero on those two documents alone. Shrug instead, and that credit request becomes the floor for the next round, not the ceiling.
When the request lands, don’t counter with a number you invented at the kitchen table. Call a licensed company for a written treatment price, and if framing is involved, have a carpenter price the wood. Now you’re arguing against two written figures instead of a buyer’s guess, and guesses run high. Two other moves belong in your pocket. Do the work before settlement and hand over the invoice at closing, which keeps the contractor choice yours. Or ask the lender and title company whether funds can sit in escrow, so closing stays on schedule and the repair happens after. Some buyers would rather take the credit and hire their own guy. Let them. Cheaper than a dead contract and fresh showings.
Leverage depends on where you are, and Maryland splits hard by region. In Baltimore, homes sold for a median near $245,000 over the three months ending August 2026, up about 2 percent from a year earlier, with a typical listing going under contract in 44 days. Buyers there have room to think. Bethesda ran a median sold price around $1.35 million in June 2026 and a median of 22 days on market, roughly flat on price year over year. Faster market, less patience for objections. Anne Arundel County counted 1,260 active listings in June 2026, about 11 percent above the same month a year earlier. More inventory means buyers walk away from friction they’d have swallowed two years ago.
So what’s your timeline? That answer decides more than anything above. A seller with six months of patience plays this completely differently from one facing a job transfer in eight weeks.
Selling As-is with Insect Damage in the File
Investors buy these houses constantly. We price wood damage the way we price a roof: by the linear foot, with a cushion for whatever’s behind the drywall. No lender, no NPMA-33, no appraiser writing up the mulch line. As investor house buyers in Frederick and other Maryland cities, we can make a cash offer based on the property’s condition.
That route trades top dollar for speed and a clean close, and it isn’t right for everyone. If your house is solid, priced well, and sitting in a fast corridor, list it. For a property carrying termite history on top of skipped upkeep, or for a family already stretched thin by a second housing payment, a cash sale is math rather than surrender.
Before you call anyone, investor or agent, put the paper in one place. Every report the house has generated, treatment invoices, the bond contract if one exists, and a few phone photos of whatever’s visible in the crawl space. Sellers who show up with that file get a real number on the first visit. Sellers who show up with a story get a range, and ranges drift the wrong way later.
Get more than one opinion on the damage itself. Pest companies sell treatment, contractors sell carpentry, and neither one is the right party to tell you what the house is worth.
A homeowner in Dundalk called us after two agent listings expired back-to-back with zero written offers. Her late husband’s workbench still filled half the garage. Both inspections had flagged the same soft sill along the rear wall, where a downspout had dumped water into the soil for a decade. She’d emailed us both reports before we met, which turned the whole visit into twenty minutes instead of two weeks.
Frequently Asked Questions
How Much Do Termite Bonds Usually Cost?
Annual bond renewals run about $150 to $500 a year, with the lower end covering inspection and re-treatment and the higher end adding repair coverage up to a stated limit. Starting from scratch costs more, generally $500 to $2,500 for the initial treatment along with the first year of protection. Get two or three written prices. Numbers for the same work vary more than most sellers expect, so the check is worth an afternoon.
Does Maryland Require a Termite Inspection to Sell?
State law doesn’t mandate one. Your buyer’s lender very likely will, and on a VA loan in Maryland it’s built in, not a maybe. An appraiser who notices damage or moisture can force one on other loan types. Cash sales carry no inspection requirement at all, though a careful cash buyer still looks. Sorting out who covers those bills is a separate question, and we answer who pays for the appraisal and inspection in Maryland in its own post.
Is It Hard to Sell a House That Has Had Termites?
Harder than selling one that hasn’t, but far from impossible, and treated history bothers buyers far less than a live colony does. Your paperwork carries the day. Keep the treatment invoice, the inspector’s report, and any receipts for repaired framing, then hand all of it over early rather than letting the buyer’s inspector break the news. Houses with damage nobody fixed usually end up selling to renovators, which is a normal outcome, not a failure. If you’re weighing that route and want a straight read on what the house is worth as-is, we’re glad to look at the file whenever you’re ready.
If you’re staring at a termite report and a mortgage payment at the same time, that’s worth a conversation before you spend a dollar on treatment. 4 Brothers Buy Houses will walk the house, tell you what the damage really means for your number, and say so if listing with an agent would put more in your pocket. Call us at (202) 601-4928 . No pressure, no obligation, and no cost to find out where you stand.
Helpful Maryland Blog Articles